Does Homeowners Insurance Cover Roof Damage? A Middle Tennessee Guide
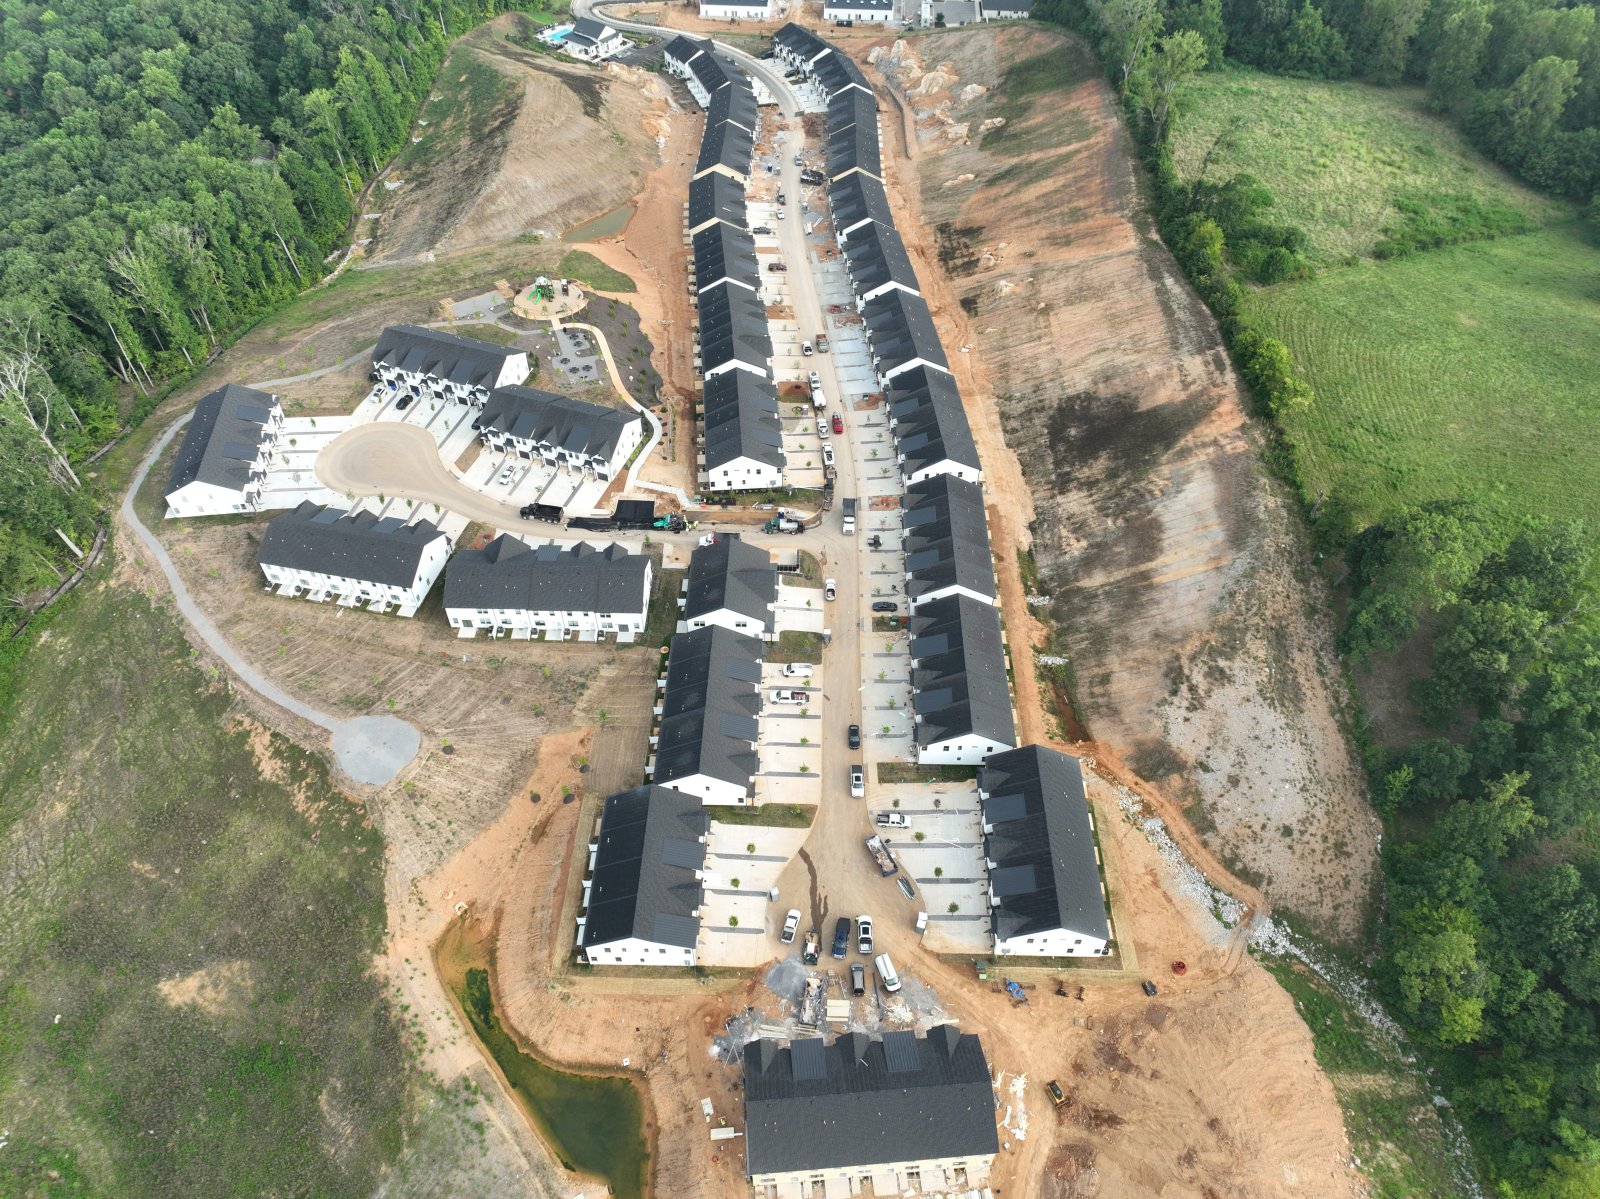
After a severe thunderstorm sweeps through Hendersonville or Gallatin, the first thing many homeowners do is look up at their shingles and ask, does homeowners insurance cover roof damage? It's a stressful moment, especially when you're facing the uncertainty of a potential leak and the fear of a denied claim. Ultimate Solution Roofing & Exteriors understands that policy jargon can feel overwhelming during a crisis. As a family owned business with 20 years of experience in Middle Tennessee, we know you want to protect your home without draining your savings on unexpected repairs.
Our team believes that clarity is the first step toward a successful restoration. In this guide, you'll learn which specific events are typically covered by your policy and how to identify the signs of storm damage that adjusters look for. We'll also explain the Tennessee "matching law" and provide a clear plan for filing a claim. From Portland to Lebanon and throughout Greater Nashville, we provide the professional documentation needed to help you move from an initial assessment to a fully restored roof. If you have questions about your specific situation, you can reach us at (615) 389-7792.
Key Takeaways
- Understand that most policies only cover "sudden and accidental" events like storms, which helps answer the common question: does homeowners insurance cover roof damage?
- Identify specific signs of wind and hail damage, such as creased shingles or impact marks on metal vents, that typically qualify for restoration coverage.
- Learn why insurers often deny claims based on natural wear and tear or a lack of routine maintenance rather than storm-related events.
- Differentiate between Replacement Cost Value (RCV) and Actual Cash Value (ACV) to see how your roof’s age and condition impact potential payouts.
- Discover how a professional inspection from Ultimate Solution Roofing & Exteriors provides the detailed documentation and photography required by insurance carriers.
Does Homeowners Insurance Cover Roof Damage? The Core Answer
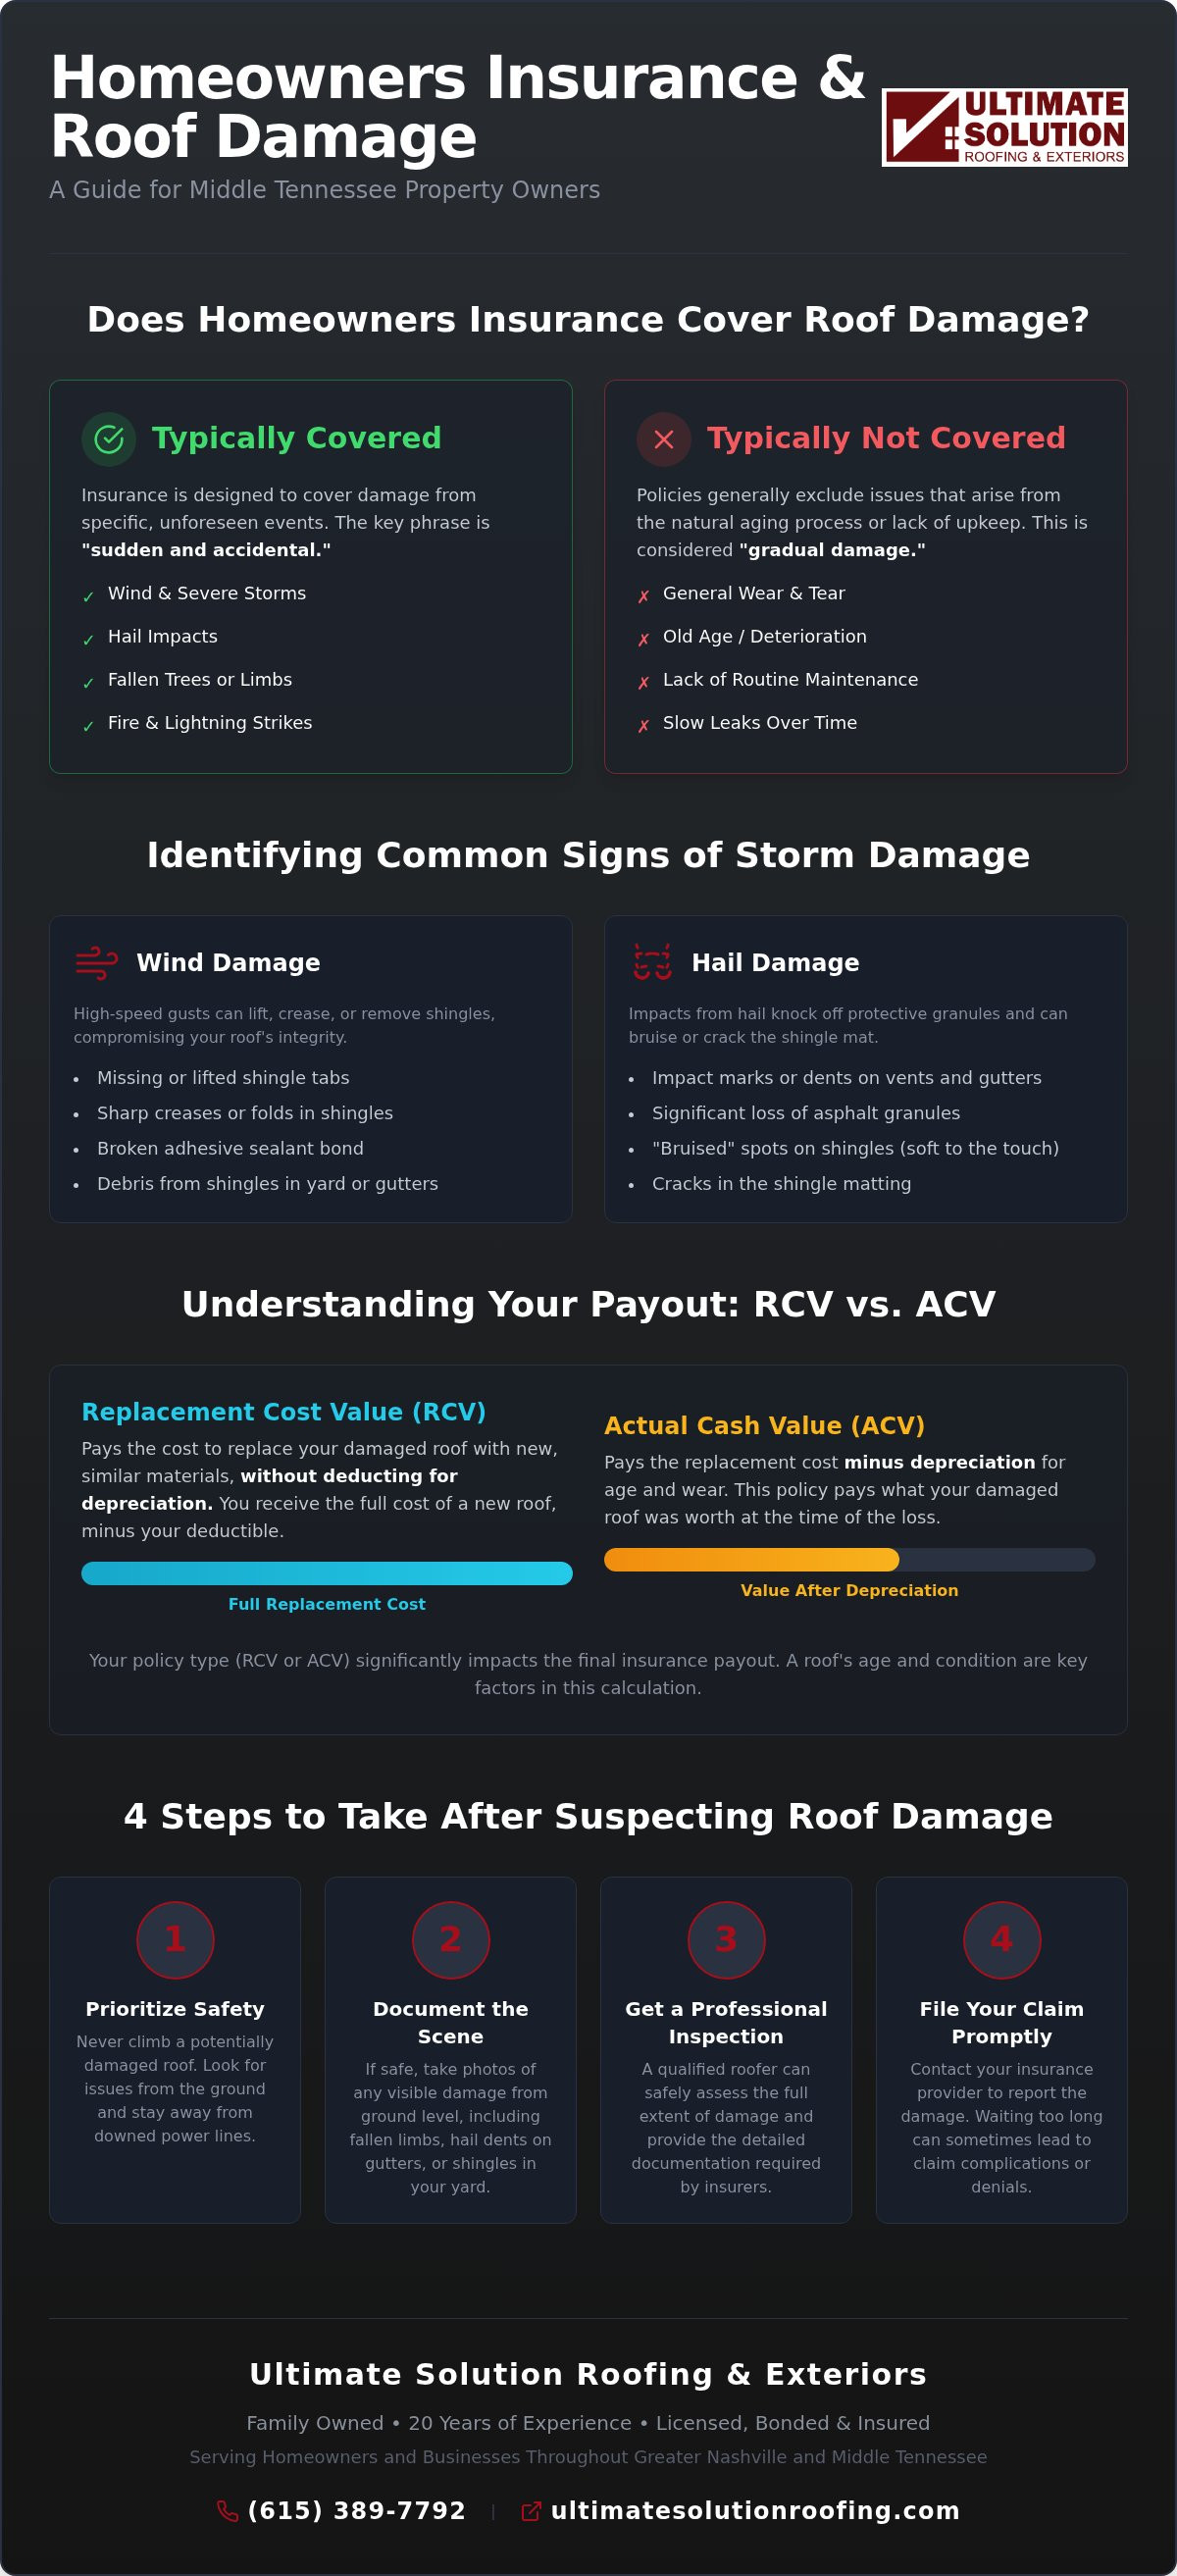
Most property owners in Middle Tennessee want a simple answer to a stressful question: does homeowners insurance cover roof damage? For the majority of standard policies, the answer is yes, provided the damage is "sudden and accidental." Ultimate Solution Roofing & Exteriors helps clients understand that insurance is designed to protect against specific, unforeseen events rather than the natural aging process of a home. A standard HO-3 policy typically covers the roof structure under "Dwelling Coverage," which protects the physical bones of your house from a list of specific risks.
Understanding property insurance basics is the first step in determining what your carrier will pay for. Most policies distinguish between the roof system itself and the personal property inside your home. If a storm rips off shingles and water ruins your furniture, two different parts of your policy may apply. Our team focuses on documenting the external structural damage to ensure your dwelling claim is based on accurate, physical evidence of a "covered peril," such as wind, hail, or fallen trees.
Sudden vs. Gradual Damage: Why Timing Matters
Timing is everything in the insurance world. Carriers view "accidental" occurrences as events that happen without warning. A tornado or a severe hail storm in Gallatin is a sudden event. Conversely, a slow leak that has been dripping in your attic for three years is considered gradual damage. Most policies require homeowners to report damage promptly. If you wait months to file after a known storm, the carrier might argue that the damage worsened due to neglect, potentially leading to a denial. Ultimate Solution provides detailed insurance solutions by performing inspections immediately after weather events to establish a clear timeline for your claim.
The Role of Your Deductible in Roof Repairs
Your deductible is the specific amount you must pay out of pocket before your insurance coverage kicks in. In Middle Tennessee, we see two main types of deductibles. Some homeowners have a flat-fee deductible, like $1,000 or $2,500. Others have percentage-based deductibles, often 1% or 2% of the home's total insured value, which are common for wind and hail claims. It's important to know that Tennessee law requires homeowners to pay their deductible. A contractor cannot legally "waive" or "absorb" this cost. We provide transparent estimates so you know exactly how your deductible fits into the total restoration budget.
What Specific Types of Roof Damage Are Covered by Insurance?
Ultimate Solution Roofing & Exteriors helps property owners in Middle Tennessee understand that standard policies generally focus on "named perils." These include fire, lightning, and windstorms. If a lightning strike causes a fire, the resulting damage is a clear physical loss. However, for most residents in cities like Hendersonville or White House, the question of does homeowners insurance cover roof damage usually revolves around wind and hail events. While every policy is different, these sudden occurrences are the primary reasons carriers approve restoration claims.
Identifying Wind and Hail Damage in Middle Tennessee
Tennessee typically experiences 50 to 60 thunderstorms per year, which often bring high-speed gusts to Gallatin and Lebanon. These winds can lift shingle tabs or create sharp creases in the material that aren't always visible from the ground. When the sealant bond breaks, the shingle is no longer watertight. Hail presents a different challenge. It often knocks the protective granules off asphalt shingles, exposing the underlying mat to sunlight and future leaks. Our team helps property owners identify these issues on soft metals, like ridge vents and gutters, which often show impact marks before the shingles do. Understanding what homeowners insurance covers can help you decide when to request a professional assessment after a storm.
Coverage for Roof Leaks and Interior Water Damage
A common point of confusion is how insurance treats active leaks. If a tree limb falls during a storm in Portland and punctures your roof, both the structural repair and the interior water damage are typically covered. This is often referred to as an "ensuing loss." Even if a specific roof repair is debated, the damage to your ceilings or drywall caused by the initial storm event usually falls under your coverage. Ultimate Solution specializes in providing the documentation and photographs necessary to show the carrier exactly how the exterior breach led to interior issues. If you notice water spots after a heavy rain, exploring our roof repair solutions can help mitigate further damage while you wait for an adjuster.
If you suspect your property has sustained storm damage, you can schedule a professional inspection to get a clear picture of your roof's condition.
Why Would a Homeowners Insurance Claim for Roof Damage Be Denied?
Understanding the limitations of your policy is just as important as knowing what is covered. When asking, does homeowners insurance cover roof damage, you have to consider the condition of the materials before the storm hit. Ultimate Solution Roofing & Exteriors often sees claims denied because the damage was pre-existing or caused by manufacturing defects. Insurance is designed to protect you from sudden "acts of God," not to serve as a replacement for a product that was faulty from the start or already damaged before your policy began. If you bought a home in Portland or Lebanon with a 15-year-old roof that already had hail hits, your current carrier won't pay for those old losses.
The "Wear and Tear" Exclusion Explained
Wear and tear is the expected degradation of materials over a 20 to 30-year lifespan. One of the most frequent reasons for denial in Middle Tennessee is this specific exclusion. Adjusters are trained to distinguish between the circular impact of a hailstone and the natural thinning of an asphalt shingle. As a roof ages, it naturally loses granules and becomes brittle. While this makes the roof more susceptible to leaks, carriers do not view this aging process as a covered peril. Our team can help you identify whether your roof is simply reaching the end of its service life or if a specific weather event in Gallatin or Hendersonville caused the current issues.
Negligence and the Duty to Protect Property
Most insurance contracts include a "duty to protect" clause. This means the homeowner is responsible for performing regular residential roofing maintenance to prevent avoidable damage. For instance, if clogged gutters lead to ice damming or water backing up under your shingles, the carrier may deny the claim based on negligence. Similarly, if you've known about a minor leak in your White House home for months and failed to address it, the insurance company might refuse to pay for the resulting structural rot or mold damage. They view these situations as preventable through basic home upkeep.
Secondary damage caused by neglect is a major hurdle in the restoration process. If a storm punctures your roof, you're expected to take reasonable steps to prevent further interior loss. Ultimate Solution provides professional inspections to document damage immediately, helping you fulfill your obligations to the carrier. By staying proactive with maintenance and addressing small repairs through our repair solutions, you can avoid the "lack of maintenance" trap that leads to many denials. If you're unsure about the current state of your roof, call our team at (615) 389-7792.
How Does Roof Age and Condition Impact Your Insurance Coverage?
Ultimate Solution Roofing & Exteriors understands that the age of your home's exterior is one of the biggest factors in a claim's success. When homeowners ask, does homeowners insurance cover roof damage, they often overlook how much the carrier will actually pay out. A brand-new roof in Hendersonville is treated differently than one that has been shielding a home in Portland for two decades. As materials age, their value decreases, and many insurance companies adjust their coverage levels accordingly. This is why our team emphasizes the importance of knowing your policy type before a storm hits Middle Tennessee.
Actual Cash Value (ACV) vs. Replacement Cost Value (RCV)
Understanding the financial side of your policy is essential for avoiding high out-of-pocket costs. A Replacement Cost Value (RCV) policy is designed to cover the cost of replacing your roof at today's market prices, minus your deductible. In contrast, an Actual Cash Value (ACV) policy only pays the depreciated value of the roof based on its age. For example, if a 15-year-old roof in Gallatin is damaged, an ACV policy will subtract the value lost over those 15 years, leaving you to cover the difference. Our team provides specialized insurance solutions to help you understand these calculations during the restoration process.
Many carriers in Middle Tennessee now implement a "20-year rule" for asphalt shingle roofs. Once a roof passes this age threshold, the insurance company may automatically switch the coverage from RCV to ACV. They might even refuse to renew a policy until the roof is replaced. Because older roofs are more brittle, they're more likely to sustain damage during standard wind events. If your roof is nearing this age, a professional inspection is the only way to determine if a repair is viable or if the extent of the damage and the material condition make a full replacement the more logical path.
The Importance of Roof Maintenance Documentation
Keeping detailed records of your home's upkeep can be a deciding factor in a claim. If you have documentation showing that you've addressed minor leaks or replaced missing shingles in the past, it proves you've fulfilled your duty to maintain the property. This baseline of care makes it much harder for an adjuster to claim that your current issues are due to old wear and tear. Ultimate Solution recommends annual check-ups to establish this history. We document the current state of your shingles, flashing, and gutters, providing a "before" picture that is invaluable if a tornado or hail storm strikes White House or Lebanon later in the year.
What Should You Do if You Suspect Your Roof Has Storm Damage?
Discovering potential damage after a Middle Tennessee storm is a high-stress situation. Your first priority should always be safety. Ultimate Solution Roofing & Exteriors strongly advises homeowners to never attempt to climb a damaged roof themselves. Steep pitches, loose granules, and structural instability from fallen debris can lead to serious injury. Instead, perform a visual check from the ground. If you see missing shingles, dented gutters, or water spots on your ceiling, it's time to seek a professional assessment to answer the question: does homeowners insurance cover roof damage in your specific case?
While some online forums suggest calling your insurance agent immediately, our team often recommends scheduling a professional roofing inspection first. An experienced contractor can provide the detailed documentation that adjusters require, which helps prevent the confusion that often leads to claim denials. We look for specific storm-related impacts that might be missed during a quick walkthrough. By having a clear report in hand before you file, you're in a much better position to discuss the facts of the loss with your carrier.
Step-by-Step Restoration Process in Middle Tennessee
The path to a restored home begins with a methodical assessment. Our team starts by taking high-resolution photography of all storm-related impacts, including collateral damage to soft metals and siding. We then help you review your policy language to understand how your specific coverage applies to the identified issues. This preparation is a vital part of the roof damage insurance claim process. Having an expert eye during this phase ensures that the scope of work reflects the actual damage sustained by the property.
Whether we recommend a repair or a full replacement depends on several critical factors. We evaluate the roof's age, the total extent of the damage, current material condition, your home's leak history, and the expected remaining service life of the system. If the damage is localized and the shingles are in good condition, a repair may be the most efficient solution. However, if the storm has compromised the structural integrity or the roof is nearing the end of its life, a replacement might be necessary to protect your home long-term.
Working with Ultimate Solution Roofing & Exteriors
Ultimate Solution acts as a knowledgeable guide throughout the entire restoration. We coordinate with you to provide detailed estimates and photographic evidence that your carrier needs to process the claim. As a family owned business with 20 years of experience, we take pride in our regional standing and our commitment to transparency. We serve property owners throughout Greater Nashville, ensuring that every project is handled with professional restraint and excellence. If you suspect storm damage in Gallatin, Hendersonville, or Nashville, call our team at (615) 389-7792 for a free assessment.
Restore Your Home with Confidence
Understanding the specific details of your policy is the most effective way to manage a storm restoration. You now know that insurance typically covers sudden events like wind and hail while excluding the natural aging process. Identifying the difference between Replacement Cost Value and Actual Cash Value is also critical for your financial planning. When you're asking does homeowners insurance cover roof damage, the answer often depends on the quality of your documentation and the timing of your report.
Ultimate Solution Roofing & Exteriors is a family owned and locally operated business with 20 years of roofing experience. As a licensed, bonded, and insured team serving Greater Nashville and Middle Tennessee, we provide the detailed inspections and estimates needed to move your project forward. We take pride in being a dependable neighbor for homeowners in Gallatin, Hendersonville, and beyond. If you need assistance, our team is available at (615) 389-7792.
We are ready to help you navigate your restoration and ensure your property remains in capable, honest hands.
Frequently Asked Questions
Does insurance cover a 20-year-old roof?
Yes, insurance can cover a 20-year-old roof, but the type of payout often changes as a system ages. Many carriers in Middle Tennessee switch from Replacement Cost Value to Actual Cash Value once a roof passes the 20-year mark. This means the insurer will pay a depreciated amount based on the remaining service life of the shingles. Some companies in White House or Lebanon may even require a full replacement before they will renew a policy.
Will filing a roof damage claim make my insurance rates go up?
In Tennessee, insurance companies generally cannot raise your individual rates solely because you filed a claim for weather-related damage. However, if a severe storm impacts a large portion of Nashville or Hendersonville, the carrier might raise premiums for the entire area to account for the increased risk. Filing a single claim for storm damage is usually seen as a non-fault event, but multiple claims in a short period can affect your eligibility.
Does homeowners insurance cover roof leaks?
If you are asking, does homeowners insurance cover roof damage resulting from a leak, the answer depends on the cause. Policies typically cover leaks that result from a "covered peril," such as a fallen tree limb or a sudden windstorm in Gallatin. If the leak is caused by gradual wear and tear or a lack of maintenance, the claim will likely be denied. Our team recommends addressing leaks immediately to prevent secondary damage to your home's interior.
What is the difference between ACV and RCV coverage?
Replacement Cost Value (RCV) covers the full cost to replace your roof at current market prices in Middle Tennessee, minus your deductible. Actual Cash Value (ACV) only pays the depreciated value of the roof based on its age. If you have an ACV policy in Portland, you will likely face higher out-of-pocket costs because the insurance company subtracts the value lost to time. Ultimate Solution Roofing & Exteriors helps clients understand these financial differences during the restoration process.
How long do I have to file a roof insurance claim in Tennessee?
While Tennessee law allows up to three years for property damage lawsuits, most insurance policies have much stricter deadlines. Many carriers in the Nashville area require homeowners to report storm damage within one year of the event. Waiting too long can make it difficult to prove the damage was caused by a specific storm rather than natural aging. We recommend scheduling an inspection immediately after any significant weather event to document the condition of your shingles.
Can I choose my own roofing contractor for insurance repairs?
You have the legal right to choose any licensed contractor for your repairs. While an insurance company might provide a list of "preferred" vendors, you are not obligated to use them. Ultimate Solution Roofing & Exteriors provides professional documentation and detailed estimates that align with industry standards. We serve property owners in Smyrna and Murfreesboro, ensuring your project is handled by local experts who understand regional building codes and the specific challenges of Middle Tennessee weather.
What happens if my roof claim is denied?
If your claim is denied, you can request a second inspection or file a formal appeal with your carrier. Denials often happen when an adjuster attributes storm damage to "wear and tear." Ultimate Solution can review the denial letter and provide additional photographic evidence if we believe the damage was overlooked. You also have the option to seek a third-party appraisal or hire a public adjuster to resolve disputes regarding the extent of the covered damage.
Does insurance cover damage from falling tree limbs?
Damage from falling tree limbs is generally covered if the limb fell due to a sudden event like a windstorm or lightning strike. This is common in wooded areas of Brentwood and Franklin during the spring storm season. Your policy typically covers the roof repair and the cost to remove the debris from the structure. However, if a limb falls from a dead or rotting tree that was not properly maintained, the insurance company may deny the claim based on negligence.
Article by
Harry Stanley III
Harry Stanley III is a construction marketing strategist and fractional CMO at H&A Marketing. He has helped construction companies grow through website strategy, SEO, paid advertising, branding, lead generation, CRM systems, and professional content. His past work includes helping Meraki Solar generate an additional $3.7 million in revenue in his first year and supporting American Builders as a fractional CMO. Today, Harry works directly with custom home builders and construction companies to build marketing systems designed to generate qualified leads and measurable growth. https://harryandally.com