How to Maximize Your Roof Insurance Claim: Tips for Middle Tennessee Homeowners
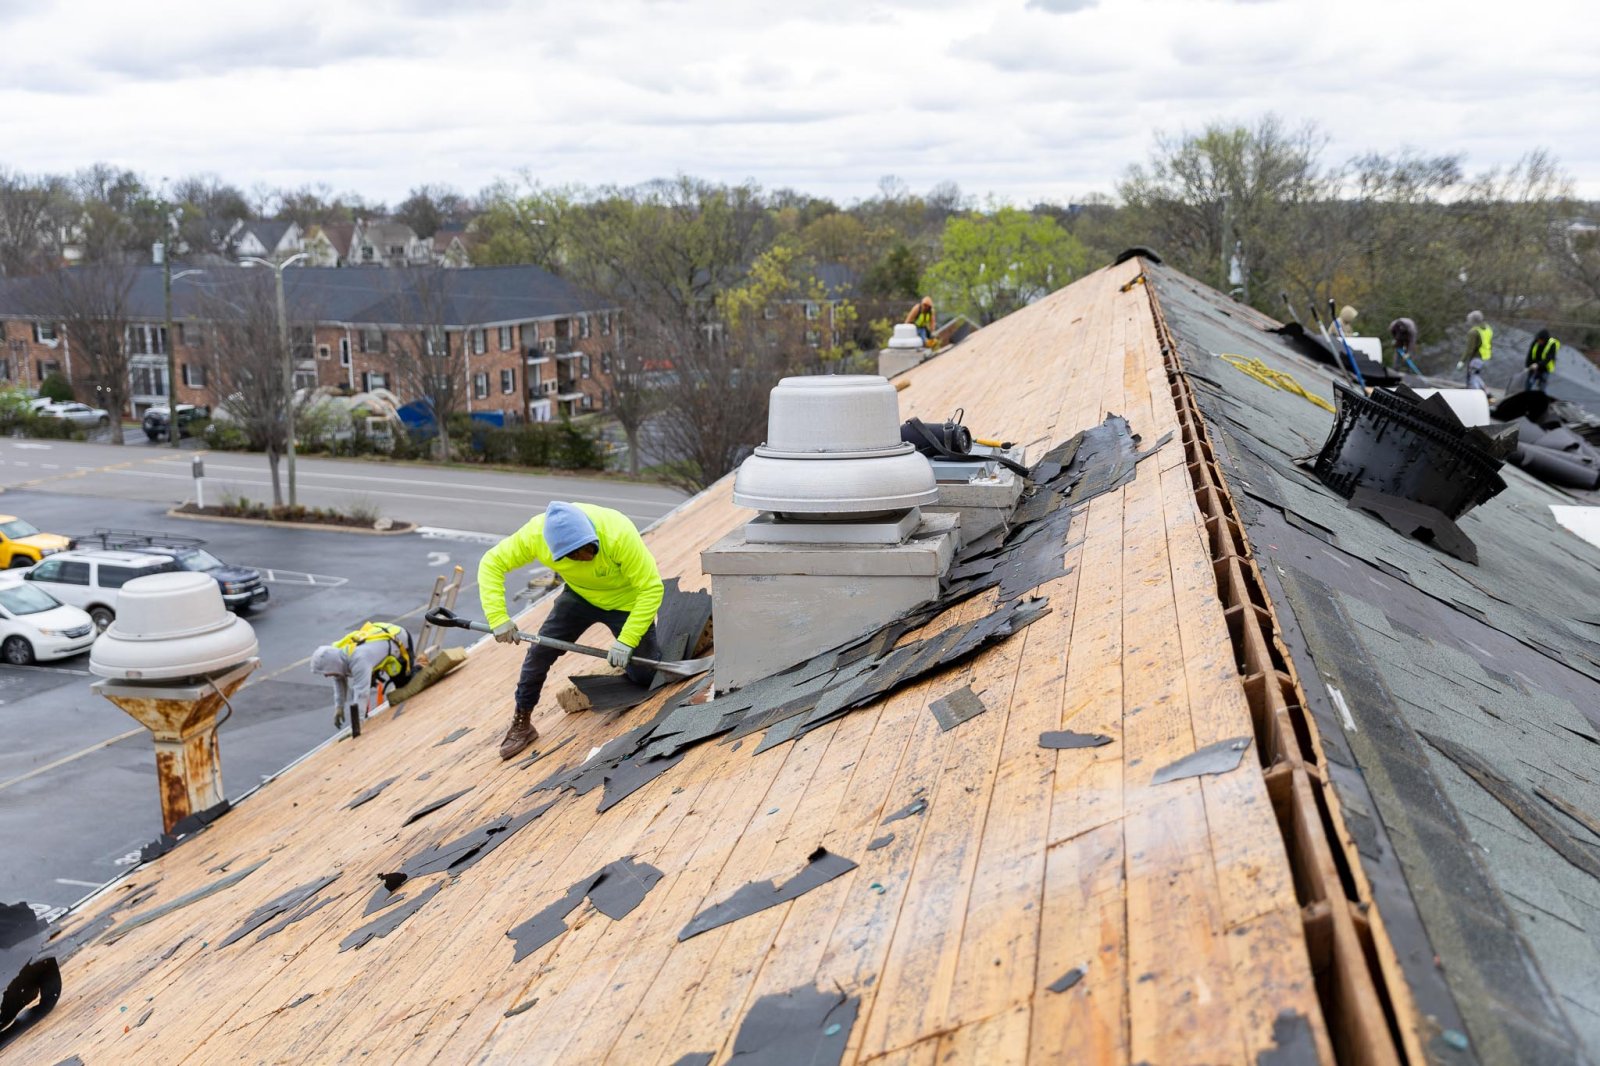
Did you know that the difference between a denied claim and a fully funded roof replacement often comes down to the quality of photos taken before the adjuster even arrives? It's stressful to stand in your yard after a Middle Tennessee storm, looking at shingles on the grass and wondering if your insurance carrier will actually cover the cost of repairs. You've likely paid your premiums for years, yet the fear of a claim denial or a confusing payout based on depreciated value is a common source of anxiety for homeowners throughout Greater Nashville.
Ultimate Solution Roofing & Exteriors understands these concerns. With 20 years of experience, our team knows that learning how to maximize roof insurance claim outcomes isn't about aggressive negotiation; it's about providing professional documentation that carriers cannot ignore. We'll show you how to identify hidden hail impact, explain the critical differences between ACV and RCV policies, and clarify the timeline for your restoration. By the end of this guide, you'll have a clear strategy to ensure your roof is restored to its full value using professional evidence and local expertise. For assistance throughout Gallatin, Hendersonville, and Lebanon, you can reach our team at (615) 389-7792.
Key Takeaways
- Learn to identify the specific signs of wind and hail damage, such as granule loss in your gutters, that often qualify for a restoration claim in Middle Tennessee.
- Discover how to maximize roof insurance claim potential by building a professional damage portfolio with high-resolution photography before your adjuster arrives.
- Understand the critical differences between Actual Cash Value and Replacement Cost Value policies to avoid unexpected out-of-pocket expenses during your project.
- Find out why having an experienced contractor from Ultimate Solution Roofing & Exteriors present during the adjuster's inspection ensures all documented damage is accurately reviewed.
- Gain insights into how local experts coordinate with carriers throughout Greater Nashville to support a thorough and fair restoration process.
Identifying Storm Damage that Qualifies for a Claim
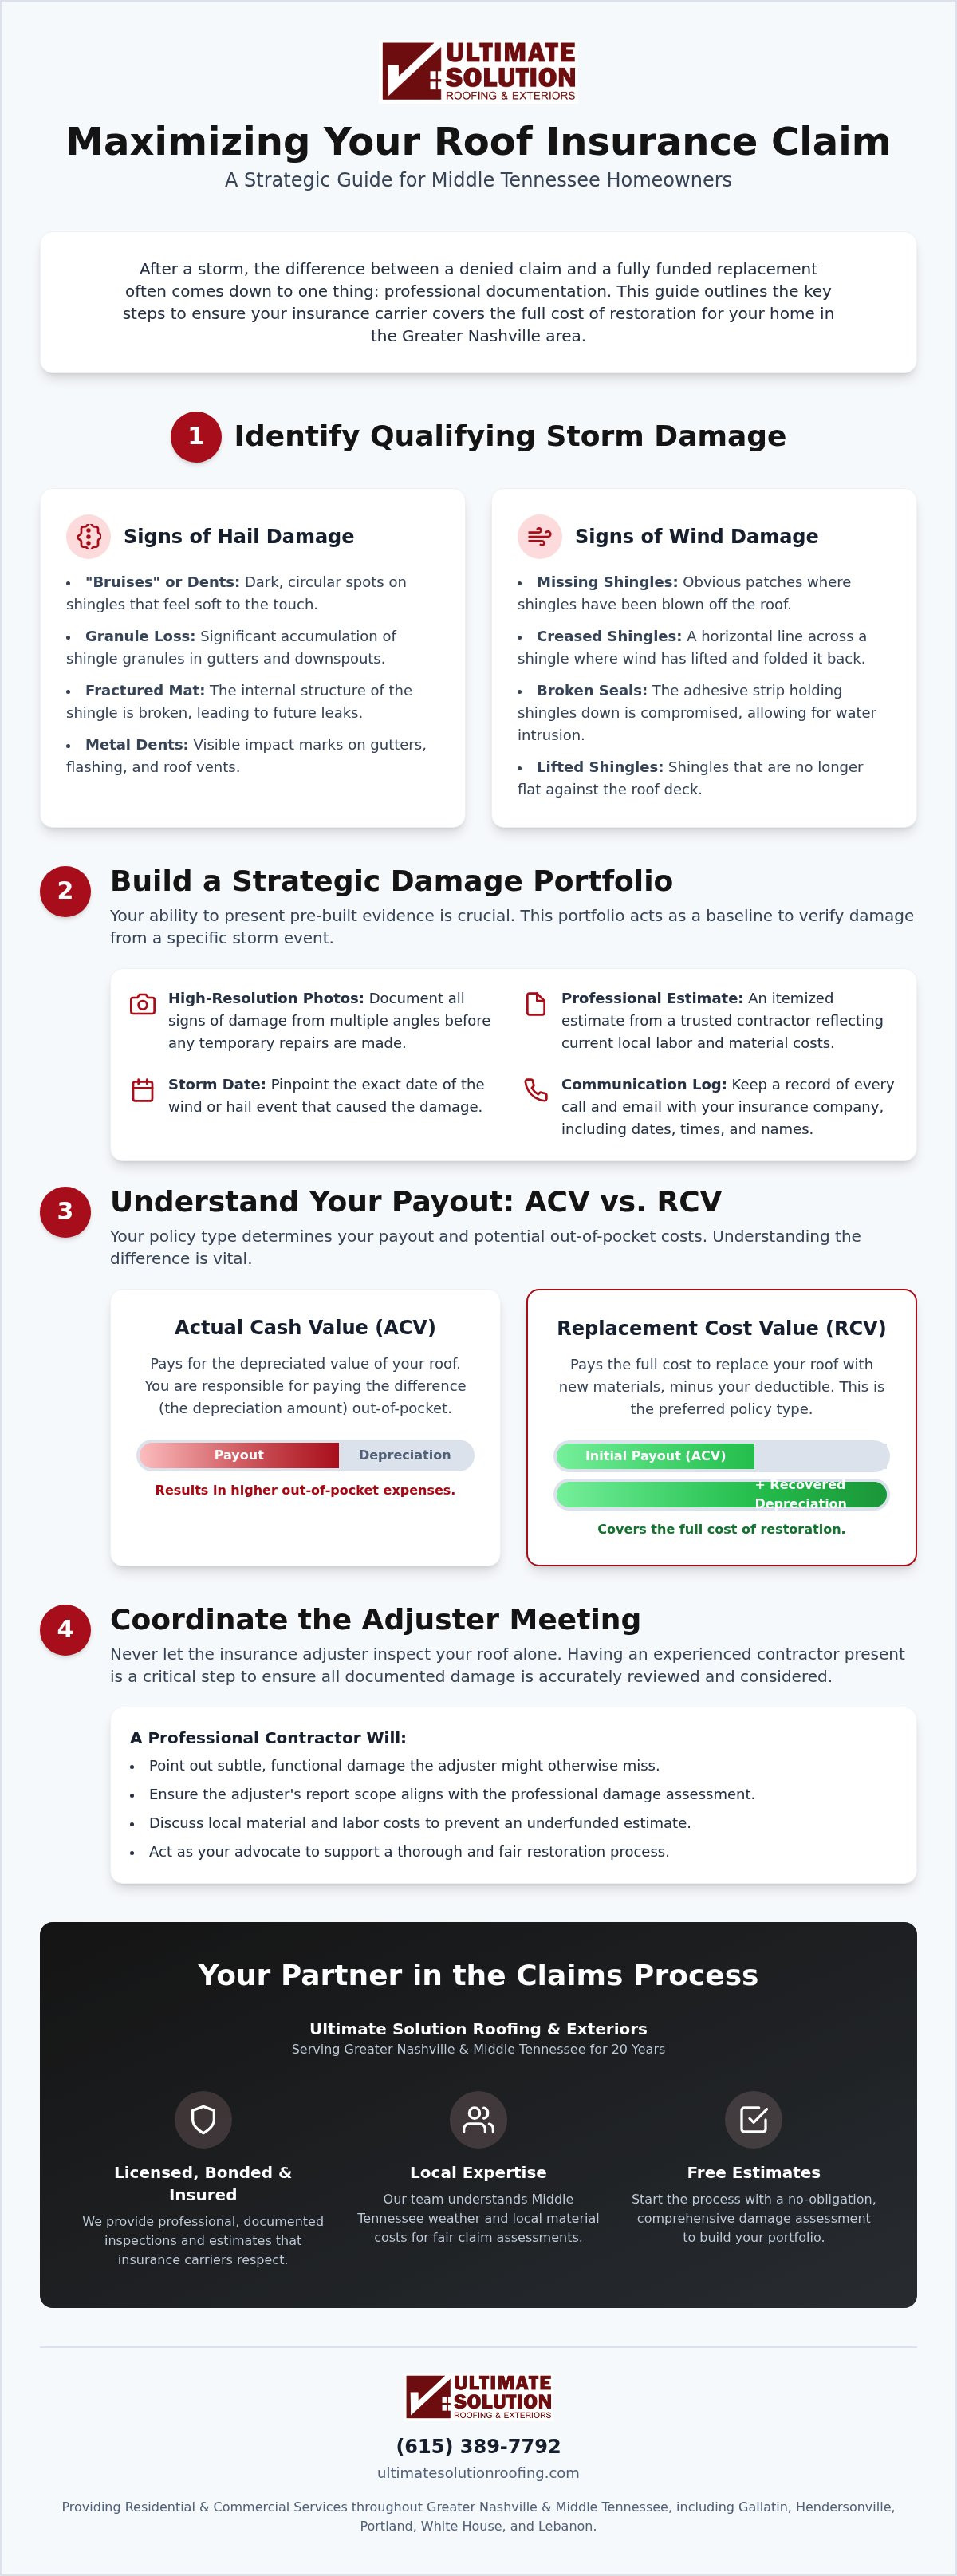
Middle Tennessee weather patterns frequently subject homes in Greater Nashville to severe wind and hail. Understanding the specific types of damage that qualify for coverage is the first step in knowing how to maximize roof insurance claim results. While missing shingles are obvious, most storm damage is subtle and easily overlooked during a standard Property insurance adjuster's walk-through.
Hail impact often leaves "bruises" or circular indentations on asphalt shingles. These soft spots indicate that the internal mat has been fractured, which eventually leads to leaks. Wind damage is equally deceptive; shingles may appear intact but could be creased or have broken adhesive seals. If you see significant granule loss in your gutters in Lebanon or White House, your roof's UV protection is compromised. This hidden damage is why many claims are initially underfunded or denied.
Signs of Hail and Wind Impact
Impact damage from hail creates a loss of granules that exposes the underlying asphalt. You should look for dark, circular spots that feel soft to the touch, similar to a bruise on an apple. High winds often cause shingles to lift and flap, creating a permanent crease across the top of the shingle even if it doesn't blow away. Functional damage is any storm-induced physical impact that reduces the roof's ability to shed water or shortens its expected service life. Identifying these issues early is critical for insurance solutions that cover the full cost of restoration.
The Importance of a Professional Inspection
Safety is the most important reason to avoid a DIY roof inspection. Climbing onto a storm-damaged surface is dangerous, especially if there are active leaks or nearby electrical hazards from fallen limbs. Ultimate Solution Roofing & Exteriors provides comprehensive inspections throughout Portland and Hendersonville to document issues that adjusters might miss. Documentation from a professional inspection is a primary factor in how to maximize roof insurance claim outcomes during the adjuster meeting. Our team identifies subtle structural shifts and uses specialized tools to verify shingle integrity. Getting a professional assessment helps ensure that the adjuster sees the full extent of the loss, which is essential for a fair settlement. We recommend scheduling an inspection immediately after any major weather event to document the damage before it worsens.
Strategic Documentation to Support Your Claim
Ultimate Solution Roofing & Exteriors recommends starting your claim process with a clear paper trail. While the insurance company sends an adjuster, their report is only one piece of the puzzle. Knowing how to maximize roof insurance claim success depends on your ability to present a pre-built damage portfolio. This portfolio acts as a baseline of evidence that helps verify that your damage resulted from a specific storm event rather than general wear and tear.
The date of the storm is your most vital piece of data. Most carriers track weather events by zip code, so linking your damage to a specific hail or wind event in Greater Nashville is essential for approval. Keep a dedicated folder for all communications. Log the date, time, and name of every person you speak with at the insurance company. This record is invaluable if delays occur or if you need to clarify how insurance companies pay out claims later in the process.
What Professional Documentation Includes
A strong portfolio includes high-resolution photos of shingle bruising, creased edges, and dents in metal flashing or gutters. These images should be taken from multiple angles to show the depth of the impact. Our team provides professional estimates that accurately reflect current labor and material costs in Middle Tennessee. This ensures the adjuster’s initial scope isn't based on generic national averages that don't account for local pricing in areas like Hendersonville or Lebanon. You can see more about our specific approach on our insurance solutions page.
Timelines for Filing in Tennessee
In Tennessee, the legal statute of limitations for property damage is three years, but your specific insurance policy often has a much tighter window. Many policies throughout White House and Portland require you to file within one year of the date of loss. Waiting too long allows the carrier to argue that your leaks are the result of neglect rather than a sudden storm. This can lead to a flat denial of your claim. For a step-by-step breakdown of this timeline, reference our Roof Damage Insurance Claim Guide for Tennessee. If you've recently experienced a storm, contact our team for a professional assessment to secure your documentation as soon as possible.
ACV vs. RCV: Understanding Your Payout Potential
Your policy type dictates the maximum amount your carrier will pay for a restoration. Actual Cash Value (ACV) policies only pay for the depreciated value of your shingles. If your roof is 15 years old, the carrier subtracts that age and wear from the payout, often leaving a significant financial gap. Replacement Cost Value (RCV) is the preferred standard for those wanting to know how to maximize roof insurance claim totals, as it covers the current market price for materials and labor. Regardless of the policy type, your deductible is a fixed out-of-pocket cost that the insurance company subtracts from the final settlement.
Ultimate Solution Roofing & Exteriors helps homeowners interpret these financial details to avoid surprises during the project. It's helpful to review the specifics of how to file a roof claim with your provider to see which coverage applies to your property. Understanding these definitions early prevents confusion when the first check arrives, as it is rarely the total amount needed for the job.
Recovering Depreciated Funds
If you have an RCV policy, the insurance company typically uses a two-check process. The first check is the ACV amount. The remaining funds, known as "recoverable depreciation," are held until the work is finished. To release these funds, you must provide the carrier with professional documentation proving the restoration is complete. Ultimate Solution Roofing & Exteriors provides the final invoicing and completion certificates needed for fund release. We coordinate this administrative step to ensure you receive the full amount your policy allows for the restoration of your Middle Tennessee home.
When Insurance Triggers a Full Replacement
Insurance carriers often use specific thresholds to decide between a repair and a full replacement. Many companies follow a "25% rule," where a full replacement is triggered if more than a quarter of the roof is damaged. Tennessee matching laws also play a major role. If your existing shingles are discontinued and a repair would result in a patchy, mismatched appearance, the insurer may be required to fund a full replacement to ensure a uniform look. The choice between these options depends on roof age, damage extent, and material condition. You can consult our repair solutions page to see if a fix is viable or if a full restoration is the more appropriate path. Never assume a replacement is guaranteed; a professional inspection is always the necessary first step.
Coordinating the Adjuster Meeting for Success
The meeting with the insurance adjuster is the most critical point in your restoration journey. While the insurance company represents their own interests, having an expert from Ultimate Solution Roofing & Exteriors on-site ensures your interests are protected through professional documentation and technical dialogue. This collaborative approach is a primary factor in how to maximize roof insurance claim results, as it ensures that the scope of work is comprehensive from the very beginning. Our team has 20 years of experience coordinating with carriers throughout Gallatin and Hendersonville to ensure no detail is missed during these evaluations.
The Value of a Joint Inspection
Adjusters often have heavy workloads and may only spend a few minutes on your roof during a busy storm season. Our team acts as a second set of eyes, pointing out subtle hail bruises that are only visible from certain angles or during specific lighting conditions. We also discuss local building codes in Greater Nashville, such as the 2026 Tennessee Residential Building Code requirements for drip edge and ice and water shields in valleys. These items are often left off initial reports if the adjuster is from out of state or unfamiliar with specific Middle Tennessee mandates. By using precise technical terms, we bridge the gap between physical damage and policy language to ensure your restoration meets current safety standards.
Handling Claim Discrepancies
Discrepancies between a contractor's estimate and an adjuster's report are common. Sometimes an adjuster misses an entire slope of the roof or underestimates the waste factor for asphalt shingles or metal panels. If this happens, our team manages the process for requesting a "supplement." A supplement is a formal request for additional funds to cover items discovered during construction or items required by local codes that were omitted from the initial settlement. If you find yourself in a situation where a roof claim is denied or significantly underfunded, professional coordination is your best path toward a fair resolution. We provide the carrier with the exact photographs and estimates they need to review these additions accurately, ensuring your project in Portland or White House is fully funded.
Why Ultimate Solution Roofing & Exteriors is Your Claims Partner
Ultimate Solution Roofing & Exteriors is a locally owned and family-operated business with 20 years of experience. We aren't a faceless corporation; we are your neighbors who take pride in our regional standing. This deep community connection is why we focus so heavily on helping you understand how to maximize roof insurance claim outcomes. We know the specific wind and hail patterns that hit Middle Tennessee, and we use that expertise to provide the detailed evidence adjusters require for fair valuations. Our team is licensed, bonded, and insured, giving you the confidence that your property is in capable hands.
Whether you require asphalt shingles for a residential project or TPO for a commercial roofing installation, our team uses high-quality materials that stand up to the local climate. Our inspections are methodical and designed to capture high-resolution photos and structural data that speak the language of insurance carriers. Our documentation process is a key part of learning how to maximize roof insurance claim potential, as it provides the carrier with undeniable proof of loss. This precision helps bridge the gap between initial, often lower, adjuster reports and the actual cost of a complete, professional restoration.
Serving the Greater Nashville Area
Our team serves property owners throughout the Greater Nashville area, providing expert guidance right where you live. We provide services throughout Gallatin, Hendersonville, Portland, White House, and Lebanon. Local knowledge is essential because Tennessee weather is unique. The high humidity and frequent thunderstorms in our region affect how shingles age and how storm damage manifests over time. We understand the nuances of local building codes and insurance requirements specific to our area. If you have concerns about your roof's integrity after a storm, call us at (615) 389-7792 for your free, professional inspection.
Comprehensive Exterior Solutions
A severe storm rarely stops at your roofline. High winds and hail often impact your entire property exterior. To provide a complete resolution, we offer specialized gutter solutions and siding options. Restoring your home to its pre-storm condition requires a comprehensive approach that addresses all damaged components simultaneously. By coordinating all exterior repairs through one trusted partner, you simplify the administrative process with your carrier and ensure the long-term protection of your property. We invite you to reach out and start your free estimate today.
Secure Your Property Restoration Today
Identifying specific storm damage patterns like hail bruising and gathering high-resolution evidence are the foundations of a successful claim. Understanding the difference between ACV and RCV ensures you're financially prepared for the restoration process. Taking these proactive steps is the most effective way to understand how to maximize roof insurance claim outcomes for your property. By coordinating with professionals who understand Middle Tennessee weather, you ensure that every detail of your loss is documented for your carrier.
Ultimate Solution Roofing & Exteriors brings 20 years of Middle Tennessee experience to every project. As a locally owned and family operated business, our team is licensed, bonded, and insured to provide residential and commercial services throughout Greater Nashville. We're here to act as your knowledgeable guide from the initial inspection to the final restoration of your home or business.
Don't let storm damage compromise your property's value. Our team is ready to help you restore the safety and integrity of your roof with professional care and local expertise.
Frequently Asked Questions
Does filing a roof insurance claim make my premiums go up?
Filing a single claim for storm damage usually won't cause an individual rate hike, as weather events are considered "Acts of God." However, insurance companies often adjust premiums for entire regions after major weather events in Middle Tennessee. If your neighbors are filing claims after a Nashville hailstorm, your rates might increase regardless of whether you file. It's often better to restore your property value when documented damage exists.
How long do I have to file a roof damage claim in Tennessee?
You typically have one year from the date of the storm to report damage to your insurance carrier. While Tennessee law allows up to three years for property damage lawsuits, most homeowners' policies include specific clauses that shorten this window significantly. Waiting too long can lead to a denial based on neglect. Our team recommends scheduling an inspection immediately after a storm in Gallatin or Hendersonville to secure your documentation.
Can I choose my own contractor for the roof replacement?
You have the absolute right to choose any licensed contractor for your restoration project. Insurance companies may provide a list of "preferred" vendors, but you aren't required to use them. Ultimate Solution Roofing & Exteriors serves homeowners throughout Lebanon and White House with 20 years of experience. Choosing a local expert who understands Middle Tennessee building codes ensures your project meets the specific requirements needed for a full and fair settlement.
What happens if the insurance check is lower than the contractor’s estimate?
Discrepancies are common and are usually resolved through the supplement process. If the initial check doesn't cover the full cost of repairs in Portland, our team provides the carrier with additional photographs and documentation. We explain the necessity of specific materials or code required upgrades. This professional coordination is a key strategy for those learning how to maximize roof insurance claim totals when the adjuster's initial scope of work is incomplete.
Do I have to pay my deductible if the damage was not my fault?
You are contractually responsible for paying your deductible regardless of who was at fault for the damage. In Tennessee, it's illegal for a contractor to "waive" or "absorb" a deductible, as this is considered insurance fraud. The deductible is simply the portion of the risk you agreed to pay when you purchased your policy. We ensure your estimate is accurate so you understand your total out of pocket costs before the project begins.
Is hail damage covered if my roof is 15 years old?
Hail damage is typically covered regardless of the roof's age, though the payout structure depends on your specific policy. If you have an Actual Cash Value policy, the carrier will subtract depreciation based on those 15 years of wear. If you have a Replacement Cost Value policy, you can recover that depreciation after the work is finished. An inspection is necessary to determine if the shingles are still eligible for a full restoration or repair.
What is a "supplement" in a roofing insurance claim?
A supplement is a formal request for additional funds sent to the insurance carrier after the initial claim is approved. This happens when our team discovers hidden damage during the tear off process or when local building codes in Nashville require upgrades not included in the original estimate. Supplements are a standard part of how to maximize roof insurance claim outcomes, ensuring that every necessary component of the restoration is fully and fairly funded.
Can I use the insurance money for something other than the roof?
Using insurance funds for anything other than the specified repairs is generally considered a violation of your policy and can lead to fraud charges. If you have an RCV policy, the carrier won't release the final depreciation payment until they receive a professional invoice proving the roof work was completed. Ultimate Solution Roofing & Exteriors provides the necessary documentation to confirm that all insurance proceeds were used to restore your property's integrity and value.
Article by
Harry Stanley III
Harry Stanley III is a construction marketing strategist and fractional CMO at H&A Marketing. He has helped construction companies grow through website strategy, SEO, paid advertising, branding, lead generation, CRM systems, and professional content. His past work includes helping Meraki Solar generate an additional $3.7 million in revenue in his first year and supporting American Builders as a fractional CMO. Today, Harry works directly with custom home builders and construction companies to build marketing systems designed to generate qualified leads and measurable growth. https://harryandally.com