Roof Claim Denied: Next Steps for Middle TN Homeowners
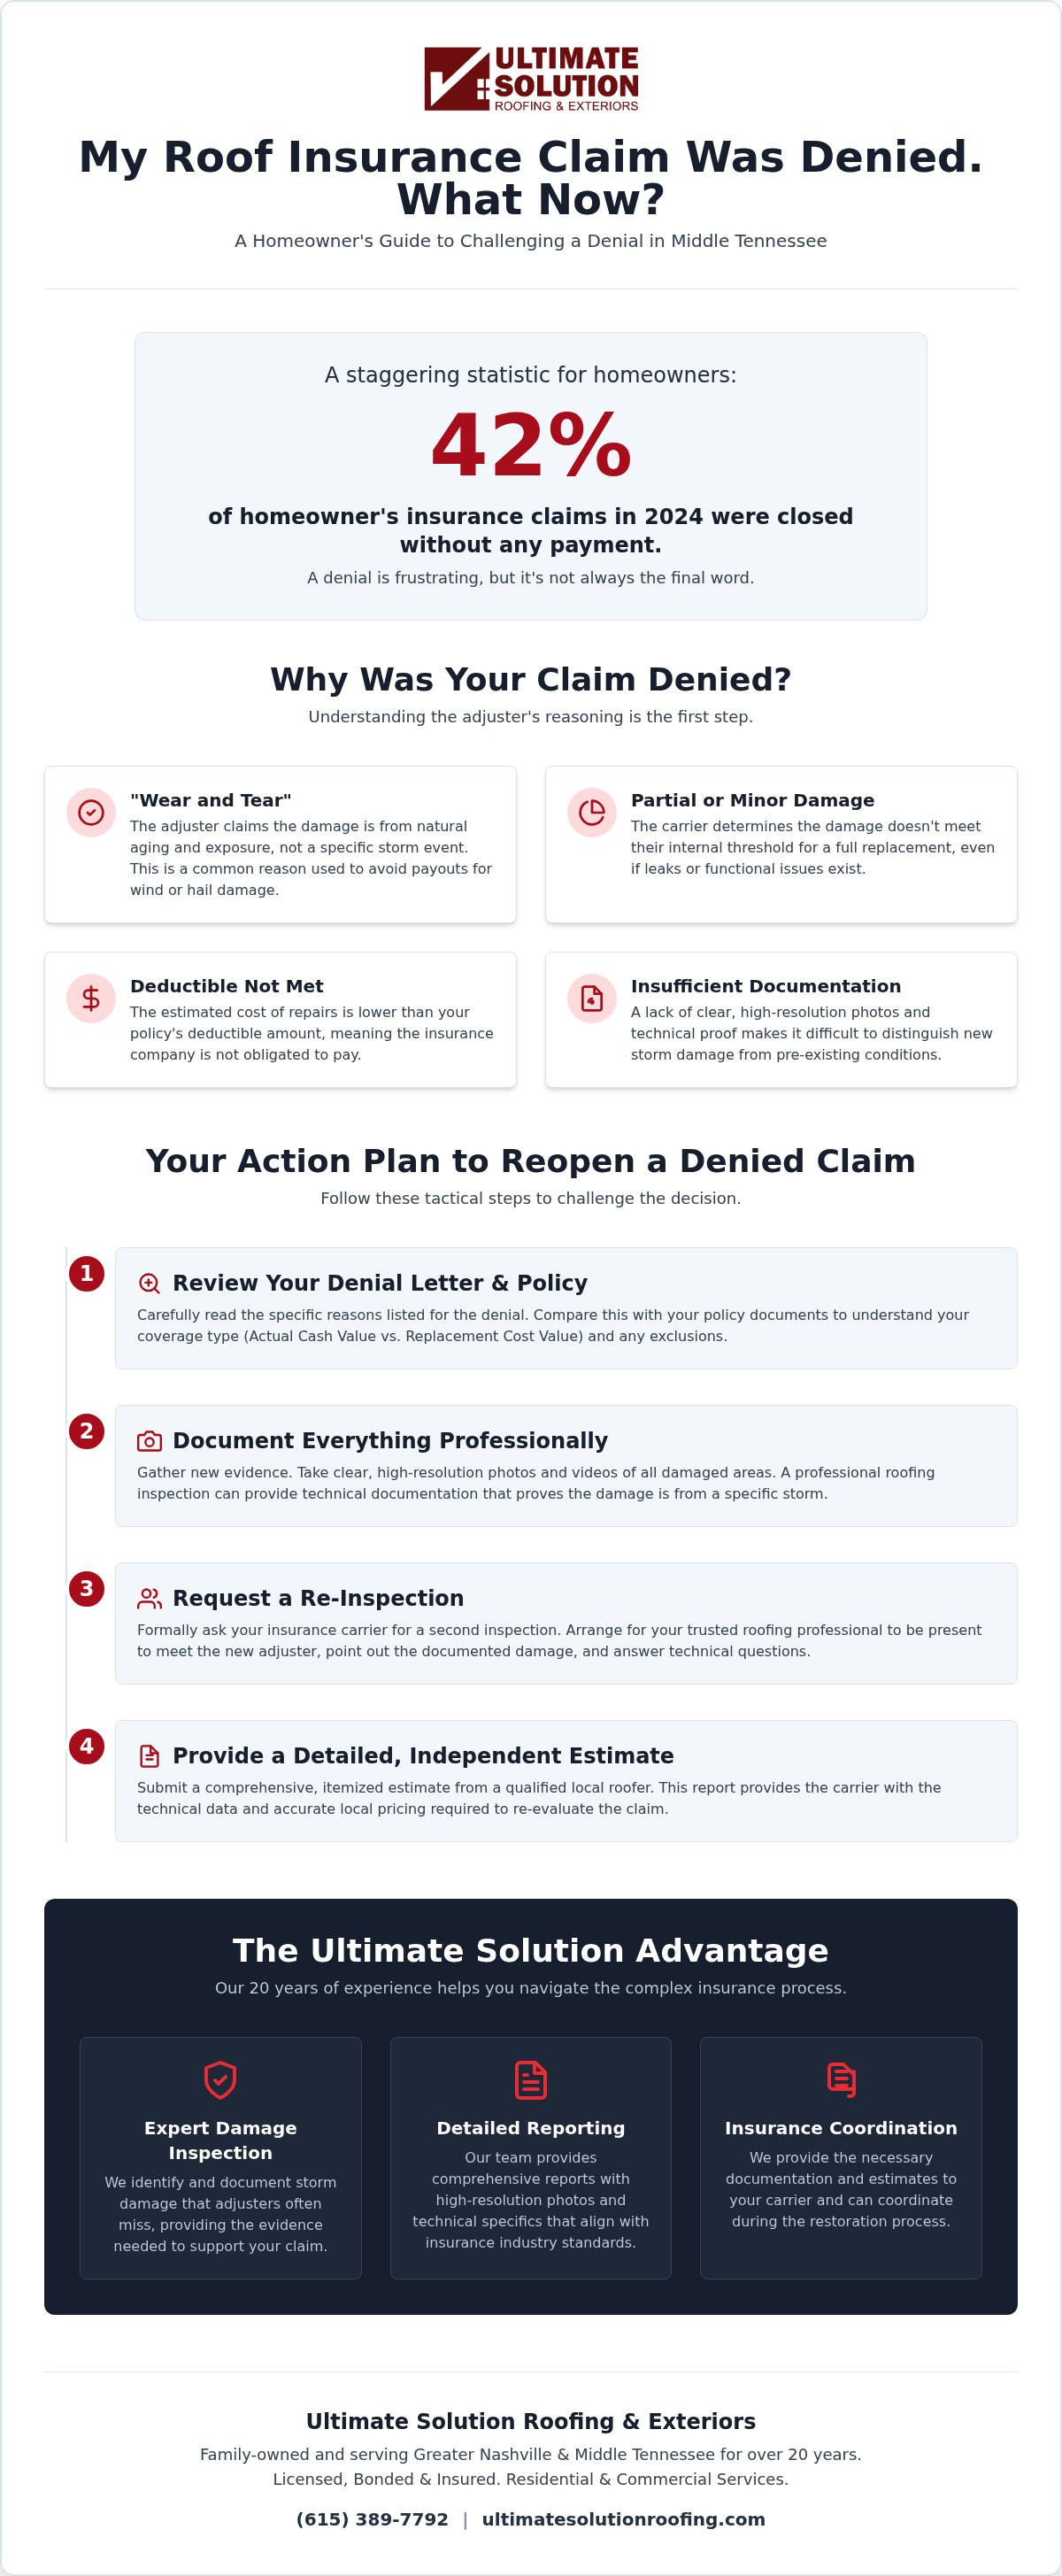
Did you know that in 2024, more than 42% of homeowners insurance claims were closed without any payment? It's a staggering statistic that feels personal when you're looking at a denial letter after a Middle Tennessee storm. You might feel ignored by an adjuster or anxious about paying for a full replacement out of your own pocket. If you're currently wondering about a roof insurance claim denied what to do, it's important to realize that a "no" isn't always the final word. Our team at Ultimate Solution Roofing & Exteriors is available at (615) 389-7792 to help you evaluate your options.
We know that many denials happen because of a lack of technical documentation rather than a lack of storm damage. We understand the frustration of being told your leaks are just "wear and tear" when you know the wind was the culprit. This guide provides the tactical steps you need to challenge a denial and restore your home. You'll learn how to request a re-inspection, document damage with professional precision, and use local expertise to advocate for your property. Whether you're in Nashville, Gallatin, or Hendersonville, we'll help you understand the process and find a clear path forward.
Key Takeaways
- Learn the specific steps regarding a roof insurance claim denied what to do, starting with a careful review of your policy and the technical reasons listed in your denial letter.
- Understand that a denial from your insurance carrier is not always a final verdict and can often be challenged through a formal appeal or a request for a re-inspection.
- Identify how professional documentation, including high-resolution photographs, can help differentiate between long-term wear and tear and sudden storm damage.
- Discover how Ultimate Solution Roofing & Exteriors uses 20 years of experience to provide the detailed reports and estimates required for the restoration process.
- Find out how to advocate for your property in Middle Tennessee by using technical evidence that aligns with the software and standards used by insurance adjusters.
Why Was Your Roof Insurance Claim Denied?
Receiving a denial letter after a severe storm in Nashville or Hendersonville is disheartening. Ultimate Solution Roofing & Exteriors has seen many homeowners struggle with this exact situation over our 20 years of experience. Often, the decision hinges on how the insurance adjuster interprets the damage compared to your specific policy language. If you are currently stuck wondering about a roof insurance claim denied what to do, the first step is identifying the technical reason for the rejection.
In Middle Tennessee, we face intense wind and hail cycles that can cause subtle but significant damage. Adjusters frequently categorize shingle loss or granule bruising as "wear and tear" to avoid a payout. Wear and tear is defined as the natural deterioration of roofing materials due to age and exposure to the elements rather than a specific, identifiable weather event. Carriers use this distinction to argue that the damage was inevitable and not caused by a recent storm in Gallatin or Portland.
Carriers also look at damage thresholds. They might find "partial damage" that doesn't meet their internal requirements for a full replacement. Your policy type also dictates the payout. An Actual Cash Value (ACV) policy only pays for the depreciated value of the roof, while a Replacement Cost Value (RCV) policy is designed to cover the cost of a new roof at current market rates. If the estimated repair cost is lower than your deductible, the claim will be closed without payment. Documentation gaps remain the most frequent cause for these denials, as a quick walk-around by an adjuster may miss technical signs of storm impact.
Common Denial Reasons in Middle Tennessee
- Pre-existing issues: Adjusters may claim the damage existed before the policy started or resulted from a lack of maintenance.
- Deductible gaps: If the damage estimate is lower than your deductible, the carrier is not obligated to pay.
- Filing delays: Many policies require you to report storm damage within a specific timeframe, often one year from the date of the event.
Understanding the Adjuster’s Summary
The denial letter contains line items that detail what the insurance representative observed during their visit. Look for terms like "mechanical damage" or "non-accidental," which are often used to dismiss valid storm claims. While some denials are based on policy facts, others may be based on an incomplete inspection. If you suspect your carrier is intentionally avoiding a valid payout, you might want to learn about Myths About Denied Insurance Claims to understand your rights as a policyholder. Ultimate Solution provides professional insurance solutions by documenting damage with high-resolution photos that adjusters might have overlooked. If you need a second opinion in White House or Lebanon, contact our team at (615) 389-7792 for repair solutions and a thorough evaluation.
Myths About Denied Insurance Claims You Should Ignore
A denial letter can feel like a closing door, but it's often just the beginning of a conversation. Many homeowners in Middle Tennessee assume that once a carrier says "no," the case is legally settled. This is one of the most damaging myths in the industry. If you are struggling with a roof insurance claim denied what to do, you should know that you aren't required to accept the first estimate or the initial decision. Insurance companies often rely on quick assessments that may overlook the specific nuances of Tennessee storm damage. Our team at Ultimate Solution Roofing & Exteriors has 20 years of experience helping neighbors see past these misconceptions.
Is an Insurance Denial Final?
A denial letter is not a legal verdict. It is a statement of the carrier's current position based on the information they have. If new evidence comes to light, such as high-resolution photos or a more detailed estimate, the claim file can be reopened. Homeowners have the right to request a re-inspection or enter into an appraisal process if there is a dispute over the damage extent. You can find more details on how these processes work by reviewing information on Why Was Your Roof Insurance Claim Denied? from the Consumer Financial Protection Bureau. Ultimate Solution has seen numerous cases where a second look led to a total reversal of the initial denial because the right documentation was finally provided.
The Role of the Independent Adjuster
It's vital to understand who is actually looking at your roof. Staff adjusters work directly for the insurance company, while independent adjusters are third-party contractors hired to handle overflow or specialized cases. Regardless of their title, they are human and can miss signs of hail bruising or wind-lifted shingles during a busy storm season in Nashville. This is why a second opinion from a local professional is essential. An experienced roofer knows exactly what to look for and how to document it to meet carrier requirements. We provide specialized insurance solutions to help you gather the technical proof needed to challenge a dismissal. Another common fear is that filing an appeal will cause premiums to skyrocket. In reality, storm damage is considered an "act of God," and Tennessee laws generally protect homeowners from individual rate hikes based on weather-related claims. If you feel your initial assessment was incomplete, you can reach out to us for a professional evaluation.
Roof Insurance Claim Denied: What to Do to Reopen Your Case
Reopening a denied claim requires a methodical approach and a clear understanding of your rights as a policyholder. If you're currently facing a roof insurance claim denied what to do, the process of reopening your case is straightforward but requires persistence. Our team at Ultimate Solution Roofing & Exteriors recommends starting with a side-by-side comparison of your denial letter and your actual policy. Look for the specific section or exclusion the carrier cited. Often, a denial is based on a narrow interpretation of damage that can be challenged with the right evidence.
Once you understand the carrier's position, follow these steps to build a stronger case:
- Request a professional inspection: Contact a trusted local roofer to perform a detailed assessment. Our team provides comprehensive roof repair solutions that include identifying damage an adjuster might have missed during a brief visit.
- Document everything: Ensure you have high-resolution photos of hail bruising, wind-lifted shingles, and any interior leaks.
- Formal Request: Send a written request for a re-inspection to your claims examiner, citing the specific new evidence you've gathered.
- Submit Evidence: Provide your contractor’s report and photos directly to the examiner to ensure they are added to your official claim file.
Requesting a Re-inspection
When you contact your claims examiner, remain professional and objective. Explain that you have additional evidence of storm-related damage that warrants a second look. It's vital to have your contractor present during this second visit. Having a representative from Ultimate Solution on-site allows for a technical discussion between professionals. We can point out specific damage markers in real-time, which often leads to a more accurate assessment. If a carrier initially refuses a re-inspection, ask to speak with a claims supervisor to discuss the documentation you've provided.
Reviewing Your Policy Endorsements
Your policy may contain specific endorsements that change how a claim is handled in cities like Nashville or Gallatin. Check if you have "Ordinance or Law" coverage, also known as code upgrade coverage. This is essential if local building codes require a full deck replacement or specific underlayment that wasn't on your original roof. Additionally, Tennessee insurance practices often involve "matching" considerations. If your specific shingle is no longer manufactured, the carrier may need to address the entire slope or roof to ensure a uniform appearance. Understanding these nuances helps you advocate for a restoration that meets local standards and protects your property's value.
When you're trying to figure out a roof insurance claim denied what to do, the strength of your appeal depends entirely on the technical evidence you provide. A simple "I disagree" isn't enough to change a claims examiner's mind. Ultimate Solution Roofing & Exteriors has 20 years of experience documenting storm damage in Middle Tennessee, and we know that professional documentation is the most effective way to challenge an adjuster's initial findings. We focus on providing a clear, evidence-based narrative that shows exactly how a storm affected your property.Photographic Evidence and Damage Mapping
Close-up photography is essential because hail bruises on asphalt shingles are often invisible from the ground or in low-resolution photos. Our team uses high-resolution cameras to capture the loss of granules and the fracturing of the fiberglass mat, which are clear indicators of storm impact. We also utilize damage mapping, which involves marking and photographing every impacted area across all roof slopes. This process shows the direction and consistency of the storm, making it much harder for a carrier to claim the damage is just localized wear. Ultimate Solution Roofing & Exteriors uses high-resolution photography to create a visual map of damage that clearly distinguishes storm impact from general aging.
We also look beyond the shingles to find collateral damage on soft metals like downspouts, box vents, and chimney caps. These surfaces show hail impact more clearly than asphalt, providing undeniable proof of a storm's severity. Our team also verifies local weather data to confirm that wind speeds or hail sizes in Lebanon or Portland matched the damage observed on your roof. This objective data helps align your claim with documented weather events, which is a vital step when you are considering a roof insurance claim denied what to do next.
Technical Estimates vs. Adjuster Summaries
Insurance adjusters use specialized software to generate their summaries, and your contractor should do the same to ensure a fair comparison. Our estimates include line items that are frequently overlooked, such as starter shingles, ridge caps, and specific types of flashing. In cities like Hendersonville and White House, local building codes often require specific upgrades during a restoration project. If these "Code Requirements" aren't included in the initial adjuster's summary, the estimate won't cover the true cost of a legal and safe installation. You can find more information on navigating these technical details in our Roof Damage Insurance Claim Guide for Tennessee.
How Ultimate Solution Roofing & Exteriors Supports Your Restoration
Ultimate Solution Roofing & Exteriors has spent 20 years serving families across Greater Nashville. We understand that a denial letter isn't just a piece of mail; it's a source of stress for homeowners who know their property has been damaged. Our team acts as a dedicated local partner to help you navigate the restoration process with technical expertise and professional documentation. We are a family owned and locally owned business, which means we understand the specific wind and hail patterns that affect Gallatin, Hendersonville, and the surrounding areas.
If you're feeling stuck and wondering about a roof insurance claim denied what to do, our role is to provide the clarity you need. We don't just look for missing shingles. We look for the technical evidence required to meet carrier standards. Our team provides professional photographs and estimates for carriers that use the same industry software they do, ensuring that your claim is evaluated based on accurate, local restoration costs. We take pride in being a dependable local expert who values transparency and thoroughness throughout every project.
Our Professional Inspection Process
When our team arrives at your Portland or White House home, we perform a comprehensive evaluation of the entire roofing system. We identify hidden damage that adjusters often overlook, such as fractured fiberglass mats or bruising that only becomes apparent upon close inspection. This thoroughness is critical because many denials are based on quick, surface-level walks that miss the structural reality of storm impact. You can call us at (615) 389-7792 to schedule your free estimate and professional assessment.
Our inspectors are licensed, bonded, and insured, providing you with a reliable report that you can present to your claims examiner. We focus on the facts of the damage, documenting everything from the ridge caps to the gutters to ensure nothing is missed in the final report. This methodical approach is designed to replace anxiety with a sense of security.
Coordinating Your Property Restoration
Coordinating a project when you've had a roof insurance claim denied what to do requires a partner who understands both the construction and the documentation side of the industry. Once the evidence is gathered, we work with you to ensure every aspect of the storm damage is addressed. Our commitment to quality craftsmanship means we don't just patch holes; we restore your home's protection using high-quality materials and proven installation techniques. Whether you need a small repair or a full replacement, our team coordinates the technical details to make the restoration process as smooth as possible. We offer specialized insurance solutions designed to help homeowners in Middle Tennessee get their properties back to pre-storm condition. For more detailed advice, you can read our Expert Roofing Insurance Claim Help in Tennessee. Our goal is to provide the resolution you need through established competence and honest communication.
Take the Next Step Toward Your Roof Restoration
A denial letter from your insurance carrier doesn't have to be the end of the road for your property restoration. You've learned that documentation is the most powerful tool you have to challenge an adjuster's initial findings. By gathering high-resolution evidence and technical estimates, you can effectively address a roof insurance claim denied what to do and request a professional re-inspection.
Ultimate Solution Roofing & Exteriors is here to act as your local advocate throughout Greater Nashville and Middle Tennessee. We are a locally owned and operated company with 20 years of exterior restoration experience. Our licensed, bonded, and insured professionals specialize in identifying the subtle storm damage that others might miss. We take pride in providing the thorough, honest assessments you need to move forward with your project.
You deserve a home that is fully protected and a partner who values craftsmanship as much as you do. We look forward to helping you restore your property and ensuring your roof is ready to handle whatever the Tennessee weather brings next.
Frequently Asked Questions
Can I appeal a denied roof insurance claim in Tennessee?
You can absolutely appeal a denied claim in Tennessee through an internal appeal process with your insurance carrier. If that doesn't work, the Tennessee Department of Commerce and Insurance provides a formal complaint process for mediation. It's often helpful to provide new evidence, like high-resolution photos or a detailed report from our team, to trigger a re-evaluation. Reopening a case is a standard procedure when homeowners are unsure about a roof insurance claim denied what to do.
How long do I have to challenge a denied claim after a storm?
You typically have up to one year from the date of the storm to report damage, but the timeframe to challenge a denial depends on your specific policy. Most carriers in Middle Tennessee follow this one-year standard for weather-related events. You should check the "Duties After Loss" section of your policy for exact deadlines. Filing your appeal quickly is essential to ensure you don't lose your right to a settlement due to a technicality.
Will my insurance rates go up if I request a re-inspection?
Requesting a re-inspection generally won't cause your individual rates to increase because storm damage is classified as an "Act of God." Insurance companies in Tennessee typically raise rates based on zip codes or regions after major weather events, rather than targeting specific policyholders for requesting a second look. You shouldn't let the fear of a premium hike prevent you from advocating for a fair assessment of your Nashville or Gallatin property.
Do I need a lawyer if my roof claim is denied?
You don't necessarily need a lawyer to challenge a denial, as most disputes can be resolved through professional documentation and the appraisal process. Many homeowners find that a detailed inspection report from Ultimate Solution Roofing & Exteriors provides enough technical evidence to overturn a decision. If the carrier continues to act in bad faith, legal counsel might be a later option, but starting with a professional roofing assessment is usually the most efficient first step.
What is the most common reason for roof claim denials in Nashville?
The most common reason for denials in Nashville and Hendersonville is a lack of technical documentation linking damage to a specific storm date. Adjusters often cite "wear and tear" or "pre-existing conditions" when they don't see obvious shingle loss. Without clear photos of hail bruising or wind uplift, carriers may assume the damage is just natural aging. Providing professional photographs and estimates that use carrier-standard software can often bridge this documentation gap.
What should I do if the adjuster says it is just "wear and tear"?
You should seek a second opinion from a local restoration expert if an adjuster claims your damage is just wear and tear. Real storm damage like hail bruising can look like natural aging to an untrained eye or an adjuster in a rush. Our team helps you identify specific markers of storm impact that differentiate it from general deterioration. This technical proof is vital when you're deciding on a roof insurance claim denied what to do next.
Can a roofing contractor help me talk to my insurance company?
Ultimate Solution Roofing & Exteriors helps by providing the technical documentation and professional estimates your carrier requires for a restoration project. While we don't act as public adjusters or legal representatives, we provide the technical evidence your carrier needs to make an informed decision. Having an experienced professional on-site in Portland or White House ensures that all storm-related issues are pointed out and recorded in the official claim file.
Is it worth filing a claim for a small amount of damage?
It is generally worth filing a claim because minor storm damage can lead to significant structural issues and leaks if left unaddressed. Even if the visible damage seems small, the integrity of your shingle mat might be compromised, shortening the service life of your roof. We recommend getting a free estimate and professional inspection in Lebanon or Smyrna before making a decision. This allows you to compare the actual repair cost against your policy deductible.
Article by
Harry Stanley III
Harry Stanley III is a construction marketing strategist and fractional CMO at H&A Marketing. He has helped construction companies grow through website strategy, SEO, paid advertising, branding, lead generation, CRM systems, and professional content. His past work includes helping Meraki Solar generate an additional $3.7 million in revenue in his first year and supporting American Builders as a fractional CMO. Today, Harry works directly with custom home builders and construction companies to build marketing systems designed to generate qualified leads and measurable growth. https://harryandally.com