How to Dispute Lowball Insurance Roof Estimate Gallatin TN: A 5-Step Guide
Learning how to dispute a lowball insurance roof estimate in Gallatin, TN starts with detailed photographic evidence of storm damage and a comprehensive, itemized line-item scope from a licensed contractor that challenges the insurer’s initial settlement proposal. Middle Tennessee homeowners receive complete inspections and detailed documentation from Ultimate Solution Roofing & Exteriors to strengthen their storm damage claims. Reach out by dialing (615) 389-7792 to claim your Free Estimate today.
Key Takeaways: To dispute a lowball insurance roof estimate in Gallatin, submit a contractor's itemized line-item scope and photographic evidence to trigger a formal on-site re-inspection.
- Compare the insurer's payout against local Gallatin material costs and mandatory Tennessee building codes.
- Skip the dispute process if your policy deductible exceeds the total estimated repair cost.
- Hire a public adjuster for scope negotiations or an attorney for total claim denials.
- Ultimate Solution Roofing & Exteriors provides the detailed documentation needed to challenge initial settlements.
Match Your Gallatin Roof Claim Dispute Strategy to the Coverage Gap
Disputing a lowball insurance estimate in Gallatin means Matching your strategy to the specific gap in the carrier’s initial payout assessment. Policyholders often receive settlements missing vital scope details, and documenting actual storm damage forces the insurer to re-examine the structural requirements.
Segment guide (pick the path that fits your file):
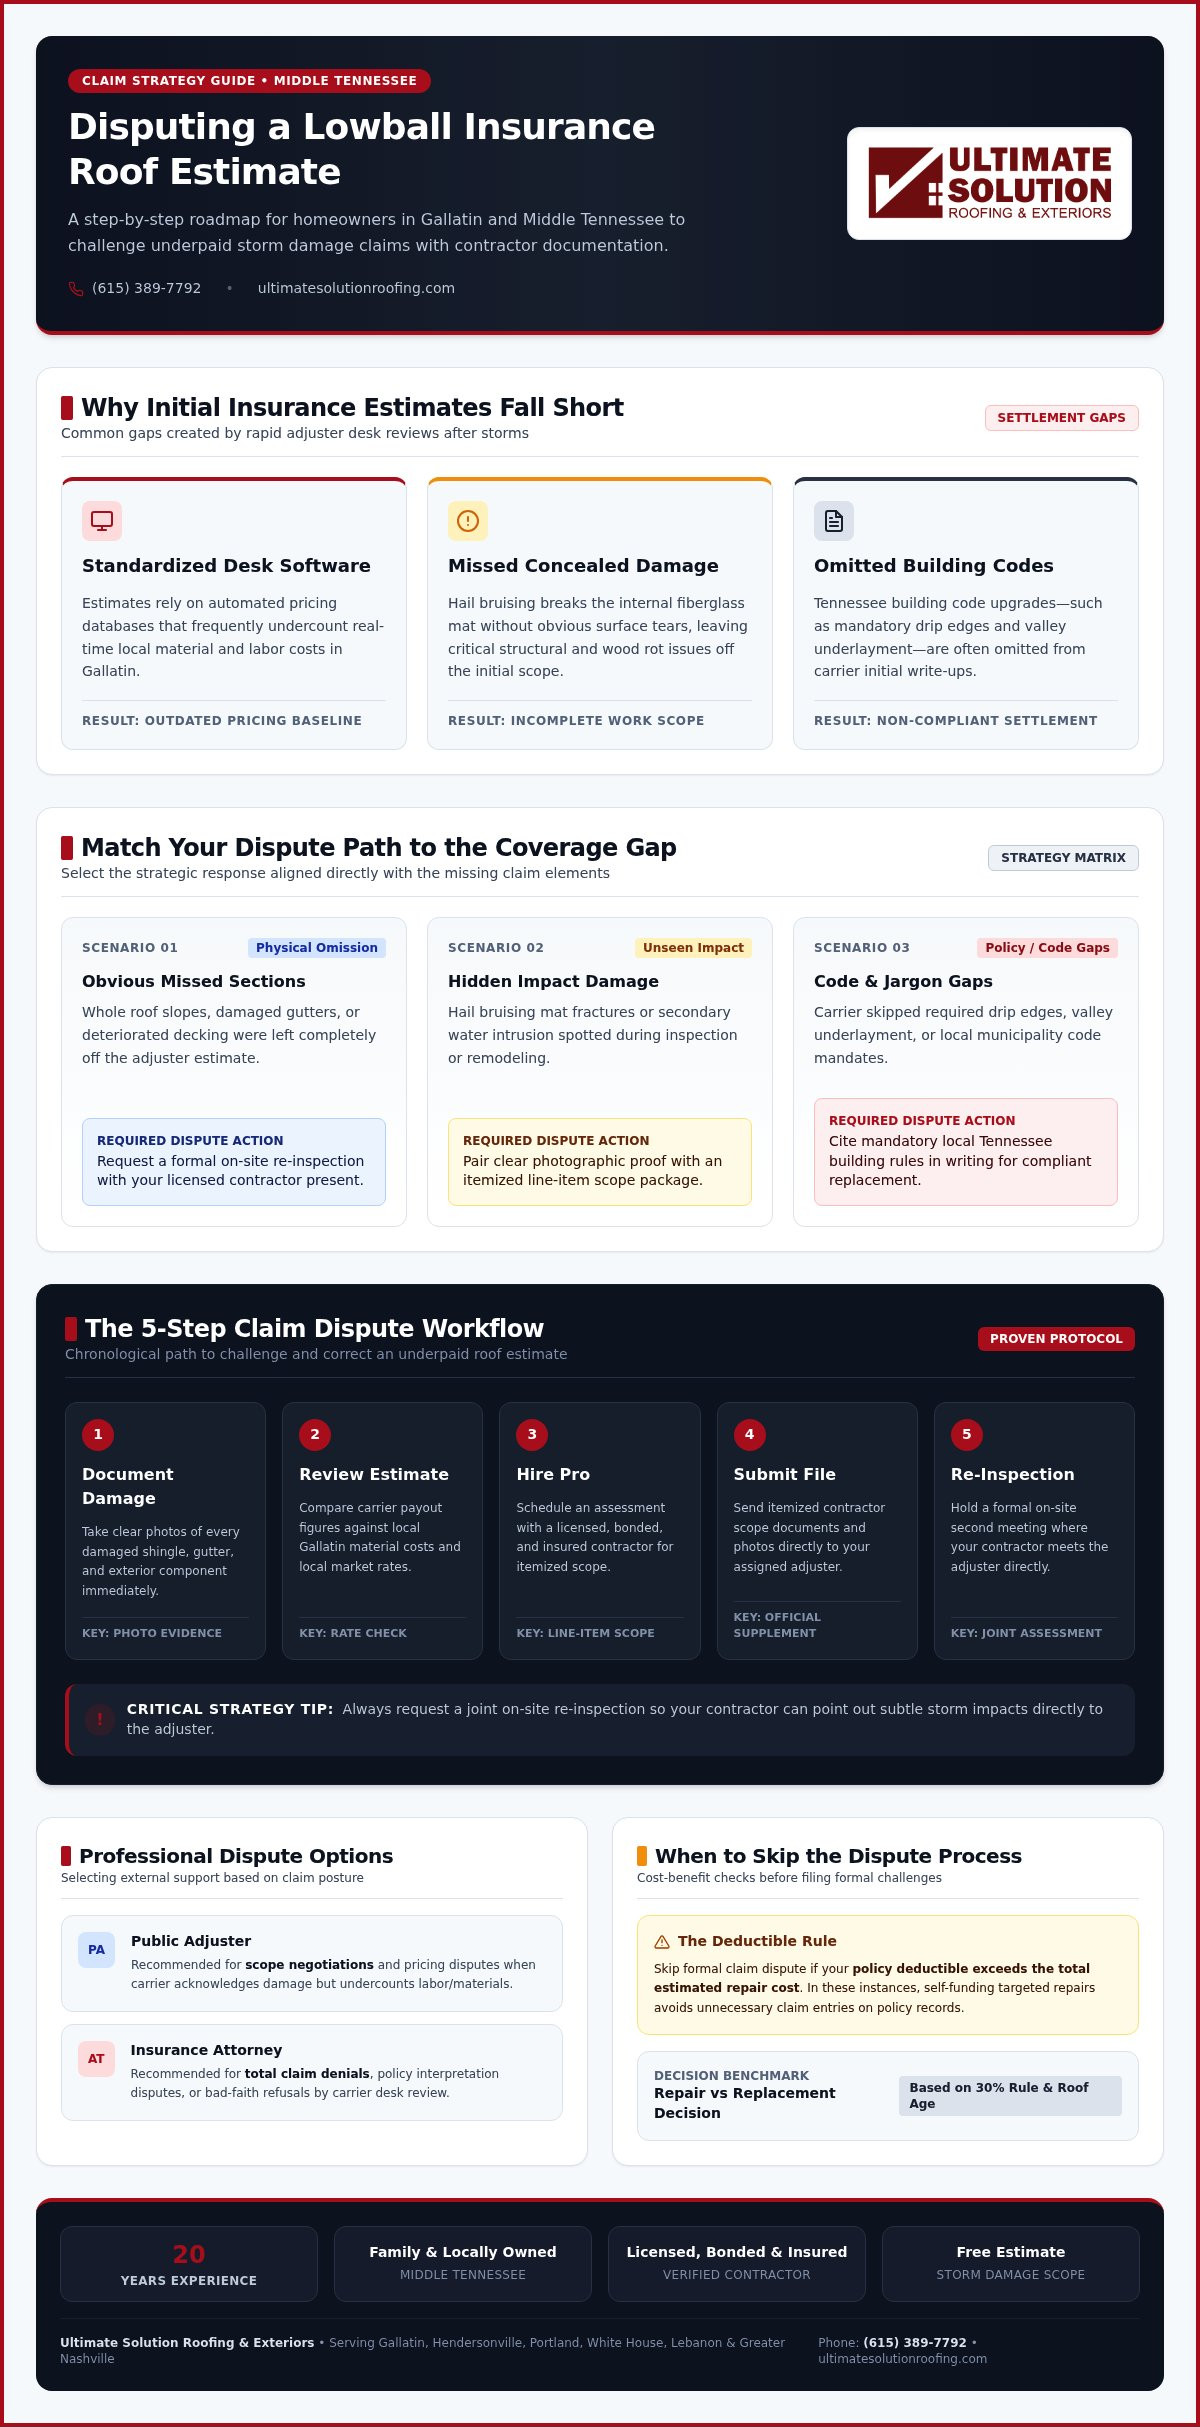
- Obvious missed sections (whole slopes, gutters, or decking left off the estimate): request a formal on-site re-inspection with your contractor present.
- Hidden impact (hail bruising, interior leaks found during other work): pair clear photos with an itemized contractor scope before you answer the adjuster.
- Code and jargon gaps (drip edge, valley underlayment, or upgrade language skipped): cite local building rules in writing so the carrier must address compliant replacement.
Selecting your approach depends on whether the company missed whole damaged sections or misapplied policy jargon (insurance secret tactics). Choosing a formal re-inspection works well for obvious physical errors; a supplemental scope package fits undercounted labor and materials.
Ultimate Solution Roofing & Exteriors is a family owned, licensed, bonded, and insured team serving Middle Tennessee. You get thorough inspections and detailed photos that help you coordinate restoration for your Residential Roofing system.
Contact our team to request your Free Estimate and align the dispute path with the gaps in your file.
Why Insurance Settlement Offers Fall Short on Storm Damage
Insurance offers often fall short because desk adjusters miss hidden structural damage or rely on standardized software that undercounts local material costs in Gallatin.
Adjusters inspect dozens of properties quickly after Middle Tennessee storms. Missing internal wood rot or understated labor rates naturally results in a lowball payout. You can explore our Insurance Solutions to see how proper documentation helps challenge these figures.
Adjusters use standard templates, and that creates blind spots. Insurance policy jargon frequently causes missed code upgrades required by local building rules (building codes), based on our direct client work. A single missing item can shrink your settlement.
Situation → action → result: You spot a small roof leak during a kitchen remodel and need the source confirmed before you file or supplement a claim. You call a licensed contractor for an immediate inspection and photo record. That documentation becomes the basis for correcting scope the desk review never saw, so interior remodeling discoveries turn into claim evidence instead of out-of-pocket surprises.
As a family owned, locally owned business, Ultimate Solution Roofing & Exteriors can help you contest an unfair estimate with direct assistance on documentation and scope language.
How to Dispute Lowball Insurance Roof Estimate Gallatin TN in 5 Steps
Disputing an underpaid roof claim requires thorough photographic evidence, detailed contractor line items, and an official request for a re-inspection.
What few people think of: small hail bruising breaks the internal fiberglass mat without showing obvious surface tears right away.
- Document damage: Take clear photographs of every damaged shingle, gutter, and exterior component.
- Review estimate: Compare your carrier’s payout against actual costs for Residential Roofing materials.
- Hire professional: Schedule an assessment with a licensed, bonded, and insured professional contractor.
- Submit paperwork: Send itemized contractor scope documents directly to your assigned insurance claims adjuster.
- Schedule re-inspection: Request an on-site second meeting to review hidden storm issues together.
Comparing an initial low settlement to actual restoration needs requires clear photographic proof. Missing hidden structural issues is as costly as ignoring a slow pipe leak behind a kitchen wall: the problem spreads while the paperwork stays incomplete. Choosing a complete professional evaluation protects long-term safety for your home.
Tip: Always request a joint re-inspection where your contractor meets the adjuster directly on site.
Among Ultimate Solution Roofing & Exteriors' Google reviews, Marsha (5★) wrote:
"My experience went very well with Tomas and his crew. He was very knowledgeable on getting the job done well and quickly. He was mindful of the cost to us and very reasonably priced. I would HIGHLY recommend his company to anyone in need of roofing services."
"Roofing Solutions did our original roof back in 2011. During the process of
"Well worth the money to have the roof done correctly and now it is all one co
Working with an experienced professional helps your home receive careful evaluation (source).com/companylist/us/mi/waterford-twp/roofing-solutions-llc-reviews-1.htm)) during complex insurance projects. Call (615) 389-7792 when you are ready for a Free Estimate and a scope you can send to the carrier.
Tennessee Building Codes That Strengthen Your Claim Dispute
Local building rules often force your insurance carrier to pay for full, compliant replacements. In field inspection work, adjusters omit mandatory local items like drip edges or proper valley underlayments to keep initial estimates low. Insurance policies typically require carriers to bring your damaged home up to current legal standards during a covered loss.
Incorporating local municipal mandates into your claim gives you a concrete standard the carrier must meet. Bypassing mandatory code requirements compromises the structural integrity of your roof and violates local law.
When you fight a low valuation, strict code compliance supports your property value with written requirements, not opinions. Local codes vary between Gallatin, Hendersonville, and White House, so specifying municipal regulations prevents adjusters from paying for sub-standard patches.
Missing these details leaves money on the table. You can consult our Gallatin team for help with policy jargon and documenting mandatory code items. More on this: Ultimate Solution Roofing & Exteriors.
As a family owned contractor with 20 years of experience, we provide a free inspection to catch missed items. Contact our licensed team at (615) 389-7792 to defend your home and schedule your Free Estimate.
Public Adjuster vs Attorney: Dispute Options Compared
Choosing between a public adjuster and an attorney depends on your specific insurance dispute stage.
In field evaluations, policyholders struggle with complex policy jargon. Using a licensed professional helps you clarify hidden terms before standard negotiation avenues close. A public adjuster handles estimate negotiations directly, while a lawyer manages legal action over actual breach of contract.
| Professional | Primary Function | Ideal Situation |
|---|---|---|
| Public Adjuster | Re-evaluates claims and estimates | Scope disputes |
| Attorney | Handles legal claims and bad faith | Claim denials |
Hiring a public adjuster fits roof scope differences, whereas an attorney suits clear claim denials. Ultimate Solution Roofing & Exteriors offers a professional inspection and honest documentation to support your claim. Request a Free Estimate from our family owned team when you need line-item clarity before you choose either path.
What Happens When You Reject an Insurance Settlement Offer?
Rejecting a low payout triggers a supplemental claim or formal appraisal, forcing the carrier to re-examine your property damage.
Homeowners often fear sudden cancellation after saying no. Carriers cannot drop your coverage simply because you dispute a lowball estimate.
An initial check can leave hidden structural issues or previous installer errors completely unfunded. Ultimate Solution Roofing & Exteriors steps in to protect your investment. The company is fully licensed, bonded, and insured to handle roofing projects. We detail every overlooked item so your actual repair costs match the true roofing project size (roofing project scope).
Accepting a rushed payout forces you to cover missed repairs out of pocket. Saying no, backed by a complete documentation set, protects your family budget and keeps your home safer through a full scope review.
Our professional roof repair team serving Gallatin, White House, and Lebanon stands ready to guide your insurance solutions. Ask for your Free Estimate so overlooked installation flaws can be documented and addressed in the revised scope.
When Formal Claim Disputes Are Not Recommended
Challenging an insurance payout makes little sense if your policy deductible exceeds the total repair cost. In field observations, pursuing a formal dispute for minor shingle loss often wastes time and risks raising your premiums unnecessarily. Fighting a claim valuation also fails when pre-existing home maintenance issues caused the structural leak.
Choosing a battle requires strategy: minor surface wear fits simple cash repairs; major storm damage fits full claim disputes.
As a licensed and insured contractor, Ultimate Solution Roofing & Exteriors can work with all insurance companies to assess your roof accurately. We serve communities from Gallatin to White House as a family owned business trusted by Middle Tennessee homeowners.
Contact our local team for a Free Estimate before you file extra paperwork.
Frequently asked questions
What if quote on roof is lower than insurance payout?
Your insurance provider bases payouts on their loss evaluation, and actual repair bills can end up lower or higher than that figure. Under standard replacement cost provisions, carriers typically release funds tied to covered repairs rather than leaving a surplus for you to pocket, so read your policy and confirm receipt and disbursement rules with the carrier before you plan upgrades. As a family owned contractor, Ultimate Solution Roofing & Exteriors assists with storm damage documentation so your payout is checked against every necessary detail. We are licensed, bonded, and insured, which allows us to work with all insurance companies to resolve scope differences transparently.
How to respond to a lowball offer from an insurance company?
Submit a formal detailed written estimate along with photo evidence from a professional inspection to request a re-inspection. Insurance adjusters sometimes overlook crucial storm damage details or miscalculate local labor rates. Our team provides clear photos and thorough documentation to help you present a complete case directly to your adjuster. You can reach us at (615) 389-7792 to request a Free Estimate before sending your final counter-submission.
What should I avoid saying to a roof insurance adjuster?
Avoid admitting fault, speculating about when damage occurred, or accepting initial verbal estimates as final settlement figures. Insurance policies contain complex policy jargon, and simple offhand comments can lead to an unnecessary claim denial. Instead, focus on verified facts and request a complete written breakdown of their proposed repairs. You can also have our experienced team meet with your adjuster on site to review the entire structure together.
Can you fight an insurance estimate?
Yes, you can dispute any low insurance estimate by providing contractor evidence, requesting a second adjuster review, or triggering your policy appraisal clause. Payout decisions are rarely final when clear documentation proves the original assessment fell short of local building codes. Ultimate Solution supports each claim consultation with technical review so you can challenge incomplete figures. Schedule a Free Estimate so our team can assess your property directly.
Final Steps to Correct a Low Settlement
You can push back against an incomplete payout offer by securing a thorough line-item damage record for your Middle Tennessee property in 2026. Practical insurance solutions help you protect your home investment when the first number comes in low. Field observations show that initial adjuster visits often overlook structural hail bruising along the roof hips and valleys. Missing these subtle impact points lowers your total settlement amount.
As a licensed, bonded, and insured professional, Ultimate Solution Roofing & Exteriors advocates for your property restoration scope with the documentation a second examination (re-inspection) requires. Call (615) 389-7792 or request your Free Estimate today.
Article by
Harry Stanley III
Harry Stanley III is a construction marketing strategist and fractional CMO at H&A Marketing. He has helped construction companies grow through website strategy, SEO, paid advertising, branding, lead generation, CRM systems, and professional content. His past work includes helping Meraki Solar generate an additional $3.7 million in revenue in his first year and supporting American Builders as a fractional CMO. Today, Harry works directly with custom home builders and construction companies to build marketing systems designed to generate qualified leads and measurable growth. https://harryandally.com